Monte Carlo Simulation: Wealth Accumulation, Returns, and Risk
Monte Carlo simulations explore how wealth may develop under different return and risk scenarios. Using an ETF savings plan, we explain 100,000 simulated market paths, volatility, inflation, fees, and the model-based likelihood of reaching a financial goal.
Monte Carlo Simulation: Understanding Wealth Accumulation, Returns, and Risk
Why a Single Return Assumption Is Not Enough
Anyone building wealth over the long term eventually asks: How much money will I have in 20 or 30 years? Traditional compound-interest calculators produce a single outcome based on a fixed return. Real markets do not grow steadily: gains can be followed by losses or extended periods of stagnation.
A Monte Carlo simulation explores this uncertainty by calculating many possible market paths under defined assumptions. It does not predict the future.
1. What Is a Monte Carlo Simulation?
Monte Carlo is a statistical technique that uses random numbers to simulate complex processes repeatedly. It was developed in the 1940s in connection with research at Los Alamos National Laboratory; Stanislaw Ulam and John von Neumann were among its leading contributors.
In financial planning, the method generates many hypothetical portfolio trajectories. Each trajectory is called a simulation path.
Initial capital and monthly contributions
Investment horizon and annual contribution increases
Expected return and volatility
Inflation and ongoing fees
2. Monte Carlo Simulation During the Accumulation Phase
During accumulation, new money is invested regularly, for example through an ETF savings plan or retirement account. The model explores the wealth that could result from a specified contribution, time horizon, and risk profile.
An inverse calculation starts with a target portfolio value and searches for the contribution required to achieve a chosen success rate within the model.
3. A Simple Example: $500 per Month for 30 Years
Initial capital: $0. Monthly contribution: $500. Horizon: 30 years. Effective annual nominal return: 7%. Volatility, inflation, fees, and contribution increases: all 0%.
Over 360 months, total contributions are $180,000. With a constant 7% effective annual return and deposits at the beginning of each month, the ending portfolio is approximately $588,032. The calculated increase is approximately $408,032. This deterministic reference example does not yet include market risk.
4. Why Volatility Matters
Volatility describes how widely returns fluctuate. A portfolio with a 7% expected annual return and 16% annual volatility can produce very different outcomes. Holding other assumptions constant, greater volatility generally creates a wider range of simulated results.
Volatility drag: If a portfolio first loses 20% and then gains 20%, an initial $100,000 falls to $80,000 and subsequently recovers to only $96,000. Although the arithmetic average of the two returns is 0%, the cumulative loss is 4%.
5. What Do 100,000 Simulation Paths Mean?
With 100,000 paths, the model calculates 100,000 potential portfolio trajectories using the same core assumptions but different random returns. More paths reduce numerical Monte Carlo sampling error, but they cannot fix unrealistic market assumptions.
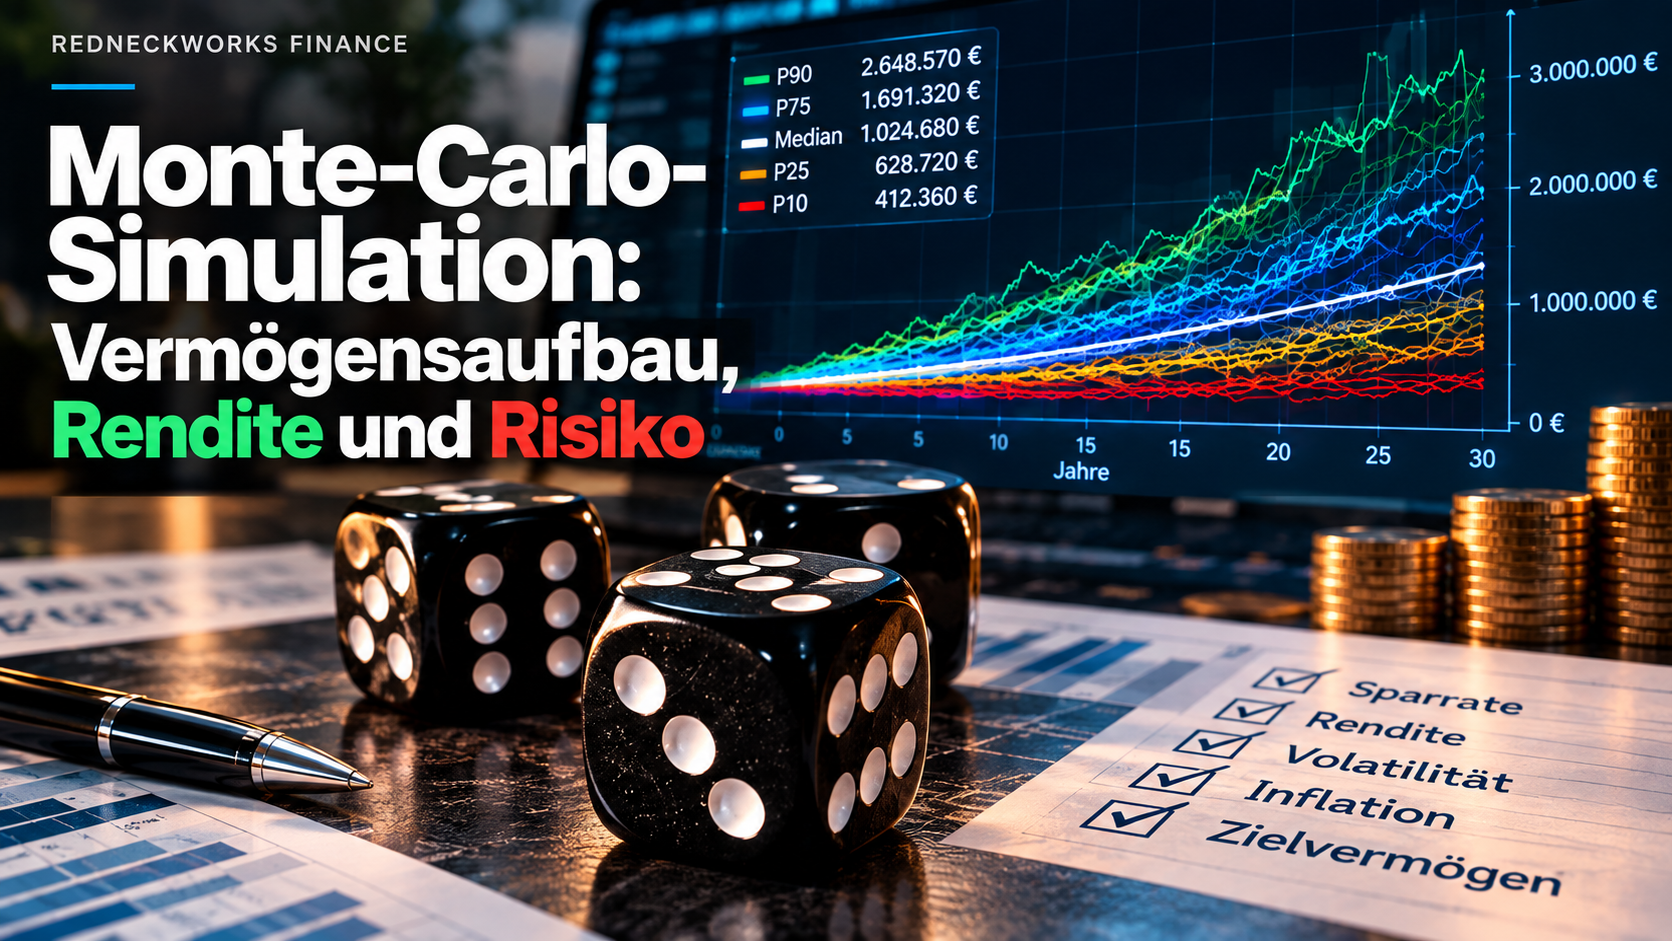
6. Percentiles: P10, P25, Median, P75, and P90
P10: Approximately 10% of simulated ending values are below this threshold.
P25: Approximately 25% are below this threshold.
P50: The median; half are below and half are above.
P75: Approximately 75% are below this threshold.
P90: Approximately 90% are below this threshold.
Percentiles describe the model distribution. They are neither guaranteed minimum outcomes nor reliable probabilities for actual future markets.
7. Inflation: Nominal Wealth Is Not Purchasing Power
An ending balance of $500,000 in 30 years represents approximately $276,000 in today’s purchasing power with constant 2% annual inflation, or approximately $206,000 with 3% inflation. Nominal and inflation-adjusted outcomes should therefore be evaluated separately.
8. Fees and Increasing Contributions
Ongoing fees erode compounding over decades. Annual increases in contributions, by contrast, raise nominal investment amounts. A 2% yearly increase may reflect rising income, but it should not be confused with an equally large increase in real savings.
9. How Much Do I Need to Save to Reach My Goal?
Inverse Monte Carlo simulation addresses a different question: What monthly contribution would allow a $1,000,000 target to be reached in, for example, 80% of simulated paths over 30 years? That success rate applies only within the specified model and is not a guarantee.
10. Parametric and Historical Simulations
Parametric models generate returns from an assumed mathematical distribution with specified return and volatility parameters. Historical bootstrap models instead resample observed returns from past market data. Both approaches depend on their assumptions and data and cannot reliably predict the future.
11. What Monte Carlo Simulations Cannot Do
Predict future returns, volatility, or inflation with certainty
Fully capture structural breaks, crises, or extreme events
Represent changing correlations or serial dependence without appropriate modeling
Account for taxes or individual decisions unless explicitly modeled
An 80% target achievement rate among simulated paths does not establish that the real-world probability is reliably known to be 80%.
12. Try a Monte Carlo Simulation Yourself
RedneckWorks Finance supports parametric and historical simulations, regular contributions and contribution increases, inflation, fees, nominal and real targets, inverse contribution searches, reproducible random seeds, and PDF reports.
Simulator: https://redneckworks.bielski.nrw/en/finance/monte-carlo
Conclusion
Monte Carlo simulations help analyze long-term wealth accumulation under uncertainty. Beyond the median, the dispersion of potential outcomes and sensitivity to returns, volatility, inflation, and fees are essential.
Notice: For educational and informational purposes only. Not investment advice, a return guarantee, or a reliable forecast of future market performance. The simulation model is undergoing technical validation (beta).